

KERJAYA Prospek Group Bhd remains well-positioned for growth, supported by a record RM6 bil order book and expanding exposure to power infrastructure, data centres (DCs) and mechanical, electrical and plumbing (MEP) works, according to MBSB Research.
The research house maintains its “Buy” recommendation on the construction group with an unchanged target price of RM3.98, implying a potential share price upside of 20.6%.
Note that Kerjaya recently secured a RM142 mil contract through a consortium with Jati Tinggi Holding Bhd and Betapac Sdn Bhd to construct the Paka Gas Insulated Substation in Terengganu for TNB.
The RM568.2 mil consortium contract sees Jati Tinggi holding a 55% stake, Kerjaya 25% and Betapac the remaining 20%.
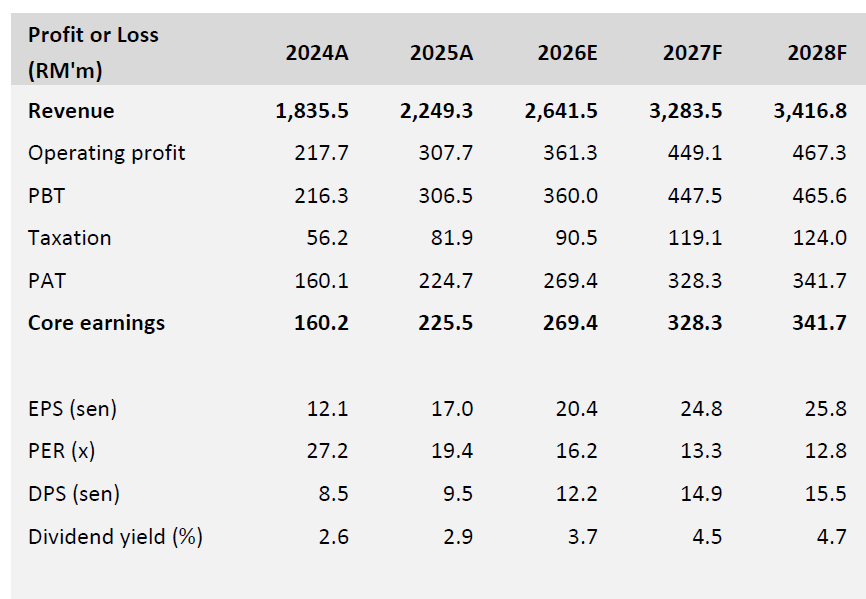
The 24-month project is expected to contribute earnings from financial year 2026 (FY20260 to FY2028.
Including this award, Kerjaya’s year-to-date contract wins have reached RM3.54 bil, nearly double the RM1.80 bil secured in FY2025 and just RM160 mil short of its previous FY2026 replenishment assumption of RM3.70 bil.
MBSB expects a potential RM300 mil internal construction award from Kerjaya’s Batu Kawan development to lift contract wins to RM3.84 bil. Consequently, it raised its FY2026 replenishment assumption to RM3.80 bil.
The latest award could increase Kerjaya’s order book from RM5.9 bil to RM6 bil before billings, providing approximately three years of earnings visibility.
External projects account for 60.7% of its FY2026 year-to-date contract wins, helping diversify its project portfolio and reduce reliance on related-party projects.
The group also has a RM2 bil tender book, with opportunities in larger DC civil and structural packages, MEP works, industrial projects and infrastructure.
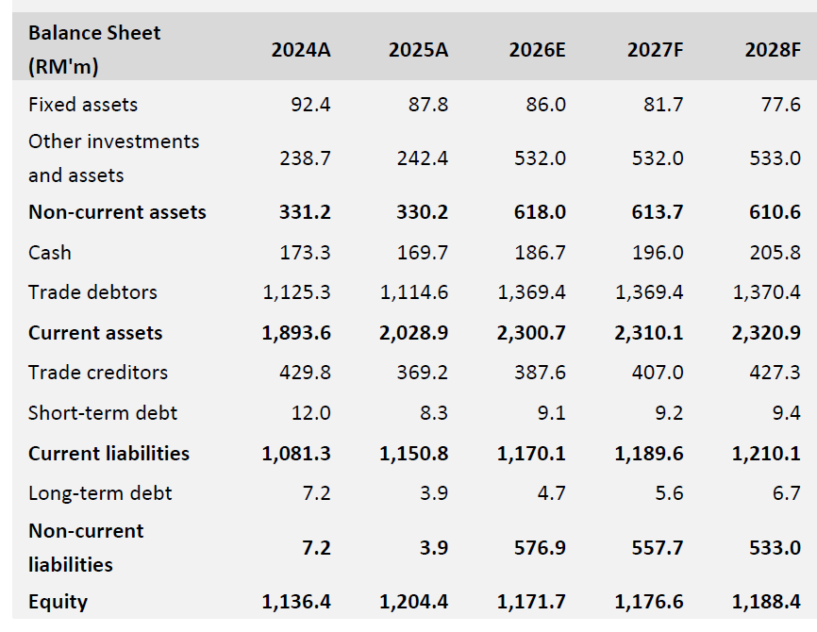
MBSB said Kerjaya’s stronger execution, diversified project mix, net-cash position and consistent dividend payouts support its valuation.—Oct 23, 2026
Main image: Kerjaya Prospek